Sharing Rental Ownership of an Inherited Home With Siblings
Sharing rental ownership of an inherited home with siblings means sharing more than rent checks. You also share repair bills, financial risk and decisions about a property that may carry emotional significance. A furnished mid-term rental can generate income while giving the family time to decide what comes next, but it works best when everyone agrees on the rules before a tenant moves in.
The starting point is not furnishing the bedrooms or advertising the home. It is confirming who can act, what each sibling owns and how you will handle disagreements.
Understand What Each Sibling Actually Owns
Being named in a will does not necessarily give you immediate authority to lease the property. Depending on the estate, an executor or administrator may control it during probate. A surviving spouse’s rights, existing debts or other estate obligations can also affect your options.
Before collecting rent, have a Texas estate or real estate attorney confirm the ownership interests, the documents establishing them and who has authority to sign a lease. Do not assume three siblings automatically own equal thirds.
Once the property passes to multiple owners, they may hold it as tenants in common. Each generally owns an undivided interest in the property rather than a particular bedroom or floor.
For siblings, successful rental ownership starts with distinguishing ownership from authority. One sibling might coordinate repairs, another might contribute startup money and a third might live nearby. Those contributions do not automatically change anyone’s ownership percentage. Document compensation, reimbursements and any proposed ownership changes separately.
Decide Whether a Mid-Term Rental Serves Everyone’s Goals
Furnished mid-term rentals commonly accommodate stays lasting a month or several months. Potential occupants include relocating households, traveling professionals and people temporarily displaced by home repairs. Actual demand depends on the property’s location, condition and pricing.
Compared with nightly rentals, longer stays can mean fewer turnovers and less frequent cleaning. They can also preserve more flexibility than a conventional year-long lease. However, furnishing costs, owner-paid utilities and gaps between occupants still affect profitability.
Ask each sibling what they need from the property. Someone who wants immediate cash may not be comfortable funding furniture and waiting for distributions. Someone who wants occasional family use may conflict with the goal of keeping the home consistently occupied.
Shared rental ownership is easier when everyone agrees whether the home is a continuing investment or a temporary arrangement before a sale. Put that purpose in writing, along with a review date.
If the family has not yet evaluated the property itself, first consider whether a mid-term rental fits your inherited home. Agreement among siblings cannot compensate for weak demand or unaffordable carrying costs.
Build a Budget Before Dividing the Rent
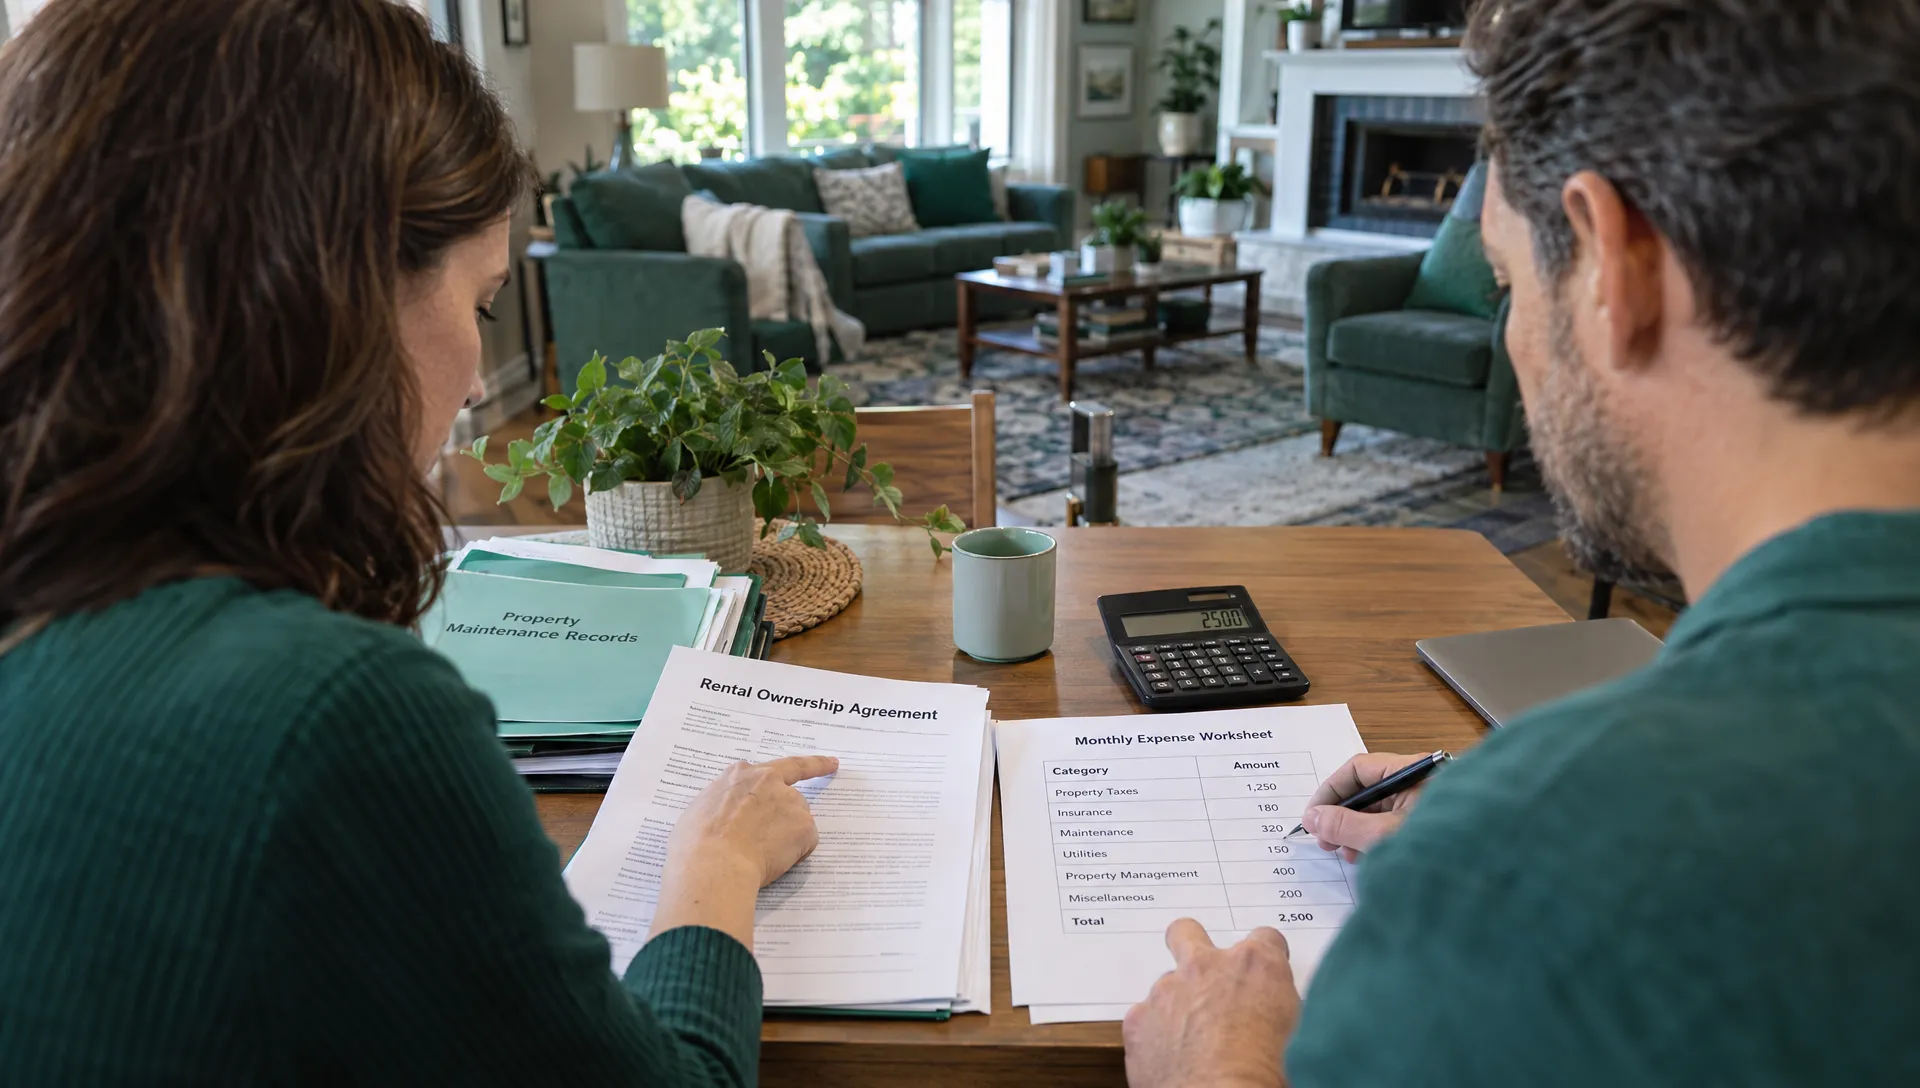
Rent collected is not the amount available to distribute. An inherited home may still have a mortgage, deferred maintenance or property taxes that change when exemptions no longer apply. Furnished rentals also need a startup budget for furniture, linens, kitchen supplies and safety preparation.
The following example is hypothetical, not a Houston rent estimate or a projection for a particular property.
| Annual cash-flow item | Illustrative amount |
|---|---|
| Rent collected, $3,000 for 10 occupied months | $30,000 |
| Property taxes and insurance | $7,200 |
| Utilities and internet | $3,600 |
| Management and leasing costs | $4,200 |
| Routine maintenance and turnover cleaning | $2,400 |
| Transfer to property reserves | $2,400 |
| Mortgage payments | $6,000 |
| Cash available for owner distributions | $4,200 |
If three siblings own equal shares and agree to equal distributions, each would receive $1,400 under these assumptions. Different ownership percentages or payment priorities would produce different results.
A workable rental ownership budget separates operating expenses, debt payments, reserve funding and owner distributions. The reserve transfer shown here is a cash allocation, not automatically a tax deduction. Mortgage principal is also different from deductible mortgage interest.
Test Vacancy, Repairs and Unequal Contributions
In the example, one additional vacant month reduces collected rent by $3,000. Distributable cash falls from $4,200 to $1,200 before any expense savings. A separate $5,000 repair would then require available reserves or additional owner funding.
Agree in advance on what happens when the property needs cash. If one sibling pays the entire repair bill, is that a reimbursable advance, a loan or an additional capital contribution? What happens if another sibling cannot contribute?
Do not leave those questions until the air conditioner fails during a Houston summer. Establish a reserve target based on the home’s condition, insurance deductibles, carrying costs and likely replacements. Identify how quickly owners must respond to a funding request.
Also consider each household’s finances. Mortgage obligations, guarantees and property losses can affect personal borrowing capacity. A sibling planning to buy a primary residence should discuss the arrangement with their lender before assuming projected rental income will offset the obligation.
Put Decision Rules in a Written Agreement
A co-ownership agreement gives rental ownership a practical operating framework. Have an attorney prepare or review it before committing substantial money or signing a lease. An informal family understanding is difficult to rely on when circumstances change.
The agreement should address these core decisions:
- Ownership and contributions: Record each owner’s percentage, startup funding and how future advances will be treated.
- Spending authority: Set limits for routine expenses, emergency repairs and improvements requiring approval.
- Voting rules: Identify which decisions require a majority, a supermajority or unanimous consent, as legally appropriate.
- Distributions: Establish reserve requirements, payment timing and any agreed repayment priorities.
- Work and personal use: Define compensation for an owner’s labor and whether family stays are permitted.
- Disputes and exits: Specify mediation procedures, buyout terms and what happens after death, disability or a proposed transfer.
For example, you might authorize a designated representative to approve budgeted maintenance while requiring broader approval for a renovation. Emergency authority should be clear enough that a leaking pipe does not wait for everyone to answer a group text.
Distinguish compensation from ownership returns. If one sibling handles regular operational work, agree on the scope, payment and tax treatment rather than letting that person informally deduct money from rent.
Which Legal Structure Fits Shared Rental Ownership?
Direct co-ownership may be simpler to establish, but the agreement still needs to govern decisions and expenses. An LLC may provide a clearer management framework and liability separation in appropriate circumstances. It does not eliminate every risk or replace insurance.
Transferring an inherited home into an LLC is not merely an administrative update. Obtain advice about title, loan restrictions, insurance, tax consequences and the costs of maintaining the entity. Do not transfer the property before confirming the implications with the relevant professionals.
Inherited property generally receives a tax basis tied to its fair market value at the decedent’s death, although exceptions and alternate valuation rules can apply. Keep the estate valuation and improvement records. The IRS explains these rules in Publication 551, Basis of Assets.
Rental income, expenses and depreciation introduce additional reporting requirements. Co-owning a rental does not automatically mean the siblings have created a partnership for federal tax purposes. The arrangement and services provided matter. A CPA can determine the appropriate reporting and allocation, using guidance such as IRS Publication 527 on residential rental property.
Confirm Insurance and Local Requirements
Shared rental ownership needs insurance suited to the property’s actual use. Tell the insurer that the home will be furnished, rented to occupants and owned by multiple people or an entity. Ask who must be listed on the policy and how liability protection applies to each owner.
Review coverage for the building, furnishings, liability and loss of rental income. Ask specifically about vacancy restrictions, water damage, wind or hail deductibles and whether separate flood coverage is appropriate for the location. A former owner-occupied homeowners policy may not fit the new arrangement.
Damage protection offered through a manager or booking service is not interchangeable with a landlord policy. Compare coverage terms, exclusions and claim requirements rather than relying only on a headline limit.
For a Houston-area property, verify the requirements of the municipality where the home actually sits, along with HOA or condominium restrictions. Minimum lease periods, occupancy rules and applicable registration or tax obligations can differ by location and rental duration.
A stay advertised as monthly does not automatically bypass every short-term rental restriction. Confirm the applicable definitions and use a lease reviewed for the intended tenancy.
Assign Management Duties Without Creating a Family Bottleneck
A common arrangement is to designate one sibling as the main contact while giving every owner access to the same financial information. The representative coordinates within approved limits, not as an unrestricted decision-maker.
Decide who handles tenant screening, lease execution, maintenance requests, utility accounts and bookkeeping. Screening criteria should be consistent and comply with fair housing requirements. Security deposits also need to be handled according to applicable law, not treated as money available for family distributions.
For siblings living in different cities, professional management can reduce the need for one person to become the unpaid local caretaker. Ask prospective managers how they handle furnished monthly stays, owner approvals, emergency repairs and financial reporting.
The family should receive a regular statement showing income collected, expenses paid, reserve balances and distributions. Major repair recommendations should identify the problem, proposed work and required approval. These owner communication and reporting workflows can help you decide what information to request.
Good reporting makes rental ownership less dependent on trust alone. It gives each sibling a way to verify what happened without questioning every purchase or asking another family member for receipts.
Agree on an Exit Before Someone Wants Out
Even a profitable arrangement can stop fitting everyone’s circumstances. One sibling may need liquidity, another may face a divorce and another may no longer want investment risk.
Your agreement should explain how an owner requests a buyout, how the property is valued and how existing debt affects the price. Specify whether the remaining siblings get the first opportunity to buy and how long they have to arrange financing.
For example, the family could agree to use an independent appraisal, then calculate the departing owner’s interest after accounting for debt and agreed adjustments. An attorney should draft the details, including how documented owner loans are handled.
Texas law provides a partition process through which a co-owner may seek division or sale of jointly owned property. Some inherited properties may qualify for procedures under the Texas Uniform Partition of Heirs’ Property Act. Whether those rules apply requires legal review.
A planned exit is usually preferable to discovering those remedies during a dispute. Shared rental ownership should also account for tenant rights: a proposed sale or family buyout does not automatically end an existing lease or guarantee vacant possession.
Frequently Asked Questions
Can one sibling rent out the inherited home without the others agreeing? Do not assume so. Authority depends on the estate’s status, title, ownership arrangement and applicable law. Confirm who can sign the lease and obtain the necessary written approvals before advertising the property or accepting money.
Should siblings split rent equally? Not automatically. Start with documented ownership interests, then account for the operating agreement, reserves and any properly documented advances or compensation. Gross rent should not be divided before the property’s obligations are covered.
Does managing the property give one sibling a larger share? Not by itself. Management work can be compensated through a written arrangement, but it should not silently change rental ownership percentages. Any ownership transfer needs appropriate documentation and legal and tax review.
Can a mid-term rental be a trial before deciding to sell? Yes, if everyone agrees and the numbers support it. Set a review date and measurable criteria, such as reserve adequacy, cash flow and workload. Coordinate lease commitments with the earliest realistic sale or possession date.
What if one sibling wants to keep living in the home? Address that before offering it for rent. Agree on occupancy terms, expenses and any payment to the other owners. Personal use can also affect taxes and insurance, so obtain advice tailored to the arrangement.
Evaluate the Property Together Before Committing
Before furnishing the home, gather the title documents, mortgage information, insurance details and repair estimates. Use them to build one budget and one written plan that every sibling understands.
Scott Property Management specializes in furnished rental properties and provides up to $1 million in property damage protection. Ask about the protection’s terms and how a mid-term rental approach could fit your inherited home. With legal authority, family decision rules and realistic financial expectations established, you can evaluate management options without leaving the difficult questions unresolved.